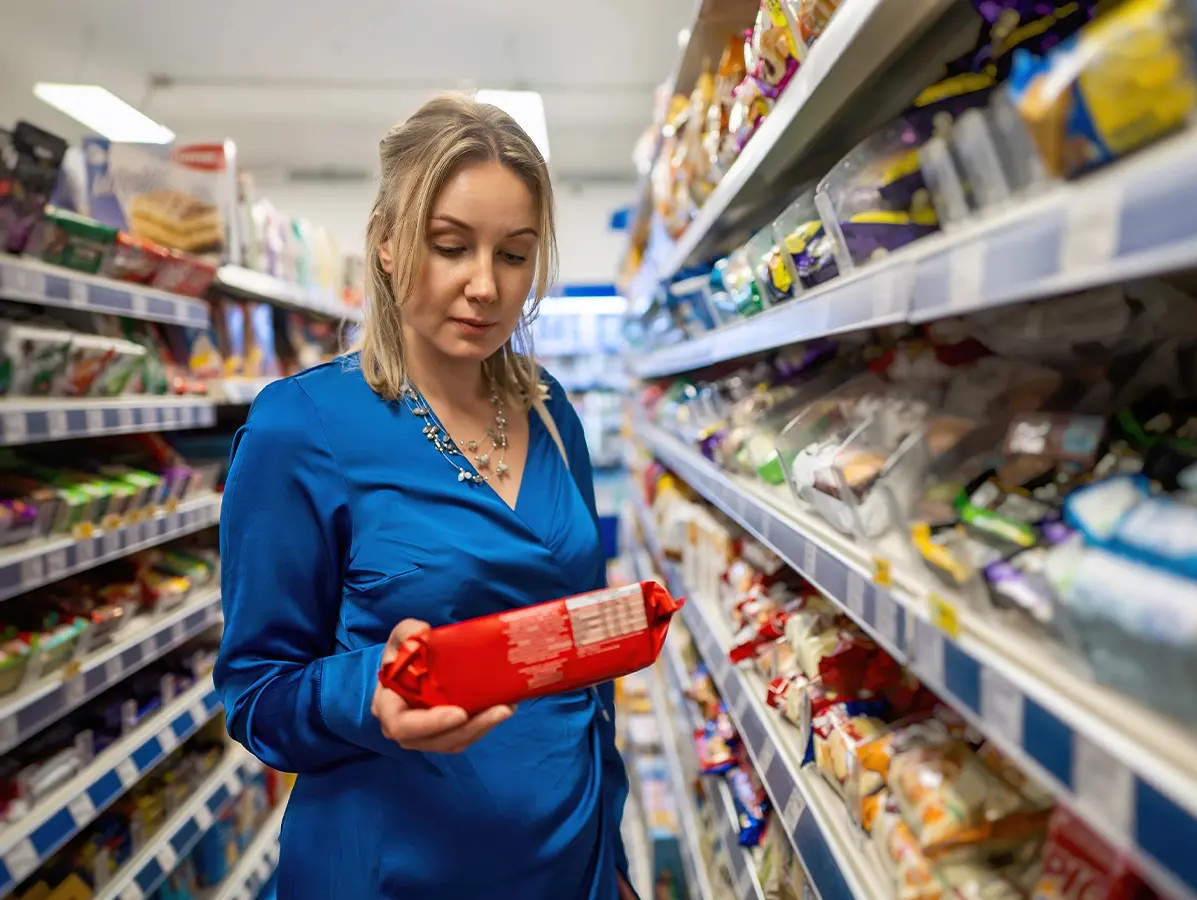
Sauces, breakfast cereals, and quark with fruit could also be subject to a sugar tax. RIVM examined two possible options at the request of VWS. The chosen threshold determines which products would be subject to the tax. For ice cream and breakfast cereals, that choice makes a clear difference.
The government aims to reduce sugar intake through higher prices. The options examined assume a tax on prepackaged food products.
The first option applies to products containing at least 6 grams of sugar per 100 grams. Products in the Wheel of Five are exempt. This includes, for example, dried fruit containing naturally occurring sugars. The remaining products account for around 42 percent of total sugar intake.
The second option sets the threshold at 20 grams of sugar per 100 grams. Under this option, products in the Wheel of Five are not exempt. Products covered by this option account for around 33 percent of total sugar intake. Both options are based on total sugar content. Naturally occurring sugars are included as well. The percentages refer to sugar intake from both food and beverages.
The tax could primarily apply to cookies, cakes and pastries, candy, chocolate, and sweet spreads. The tax could also apply to ice cream, sweeteners, and certain dairy products, such as quark with fruit. For sauces and breakfast cereals, the 6% option covers around half the amount consumed.
A higher sugar threshold reduces that share across several product categories. For ice cream, it falls from 100 to 68 percent. For breakfast cereals, it falls from 51 to 14 percent. These figures refer to the amounts consumed, not the number of products.
RIVM used data from the 2019–2021 Dutch National Food Consumption Survey and the Dutch Food Composition Database NEVO-2025. The survey includes 3,570 participants aged 1 to 79.
The data do not distinguish between prepackaged and unpackaged products. RIVM therefore included both categories in its calculations. If only prepackaged food products are taxed, the percentages are expected to be lower.
Source: RIVM
Magazine Voedingsindustrie has been made possible in part by:
© COPYRIGHT 2026 VOEDINGSINDUSTRIE | ALLE RECHTEN VOORBEHOUDEN
Powered by Wallbrink Crossmedia © 2026