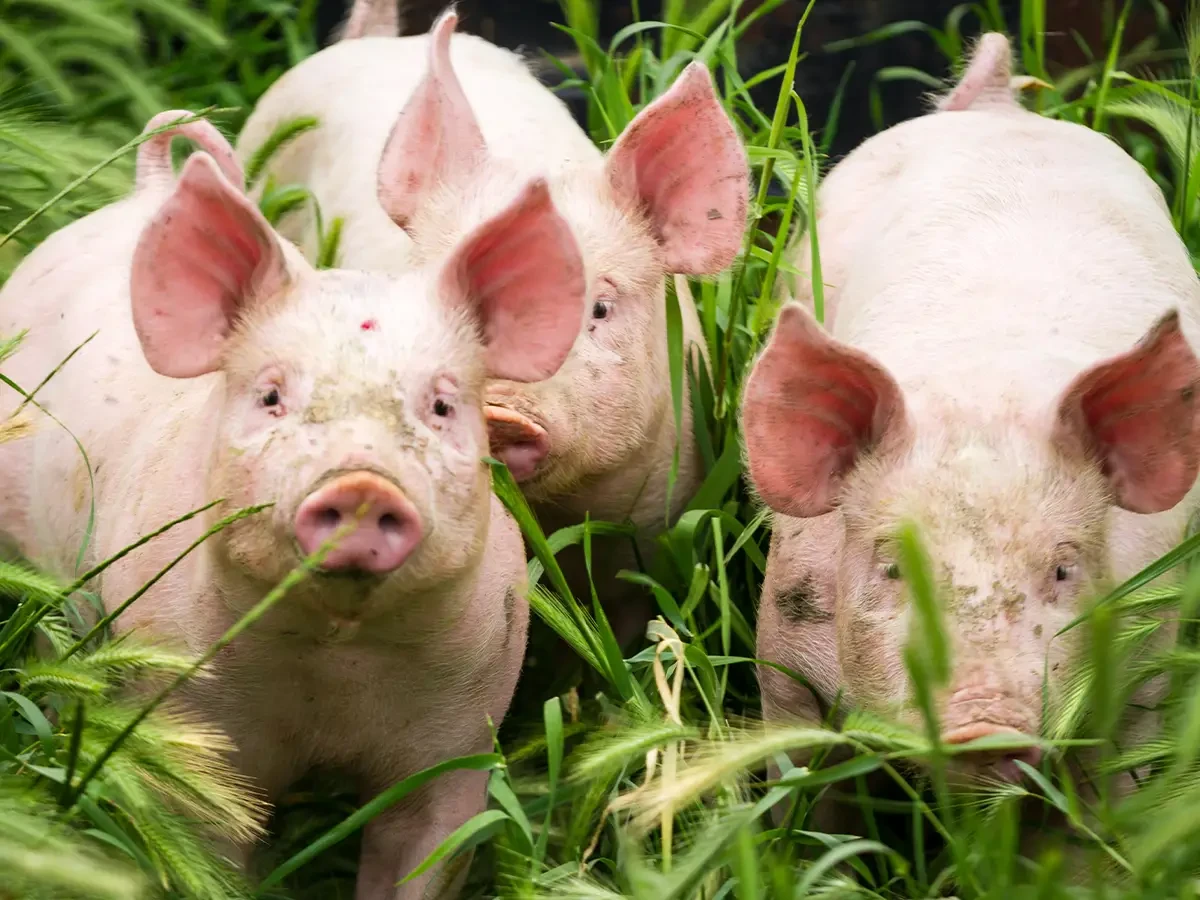
Dutch pork production fell by nearly 7% in the first seven months of the year. Yet European supply remains ample for now, according to Rabobank. Pig prices are unlikely to recover in 2026. European exports are also expected to remain under pressure in 2027.
Both slaughter numbers and average carcass weights fell in the Netherlands. Pork production in the EU-27 and the United Kingdom, by contrast, rose by around 1.6%. Production grew fastest in Denmark, followed by the United Kingdom, Poland and Spain.
Sow numbers also declined significantly in the Netherlands. The sow herd shrank by 5% between the end of 2025 and June 2026. This was the steepest decline among the eleven European countries surveyed. Together, these countries had 1.5% fewer sows than at the end of 2025. Rising productivity is offsetting part of that decline. As a result, European pig supply is falling only gradually.
Rabobank expects European pig supply to decline gradually from the fourth quarter onward. That decline is expected to continue in 2027. For now, ample supply continues to weigh on European pig prices. The bank therefore considers a price recovery this year unlikely.
Rabobank expects Dutch pig production to stabilize in 2027. This follows a sharp contraction driven by buyout schemes in 2026.
European export volumes remained largely stable in the first half of 2026. Export value fell by 12% compared with the same period in 2025. Lower pork prices and China’s smaller share of exports drove that decline.
China imported 15% less pork in the first eight months than a year earlier. Chinese imports of pork muscle cuts from the Netherlands fell by 62%. South Korea, Vietnam and the Philippines accounted for a larger share of European exports.
According to Rabobank, European exports will remain under pressure in 2027. Chinese antidumping duties weaken the competitive position of European pork in China. Brazil also remains a strong competitor in the global market.
Source: Rabobank
Magazine Voedingsindustrie has been made possible in part by:
© COPYRIGHT 2026 VOEDINGSINDUSTRIE | ALLE RECHTEN VOORBEHOUDEN
Powered by Wallbrink Crossmedia © 2026